America's Legacy Wells Are Becoming a Multibillion-Dollar Market
The problem is acute and is right at the top of the US administration's to-do list. Millions of orphaned oil and gas wells are making professional remediation a long-term growth market in the US. Zefiro Methane, together with its subsidiary Plants & Goodwin, specialises in plugging orphaned wells, curbing methane emissions and subsequent site remediation. The integrated business model combines environmental protection with a tangible infrastructure need, boosted by government funding programmes and private construction projects. The expansion of energy facilities and AI data centres also creates further opportunities, as contaminated sites must be remediated before they can be put to new use. Alongside conventional well plugging, Zefiro also offers methane measurements, technical investigations and, in future, the marketing of verified emissions credits. The growth portfolio offers many avenues, and Zefiro is now showing analysts its operational execution power!
USD 40 Million in Orders Provide Visibility Through to 2029
The latest announcement signals strong medium-term revenue growth: Zefiro has a government-funded order backlog of about USD 40 million, with work scheduled through June 2029. This includes the major USD 19.6 million contract in Ohio for the remediation of around 200 priority wells, as well as another project worth USD 11.5 million. Additional federal contracts and previously undisclosed projects in Ohio complement the portfolio. Work worth approximately USD 4.9 million is expected to be carried out in the current second quarter of the 2026/27 financial year alone. It is important to note that this order backlog comprises government projects only, with business from private customers coming on top.
Another announcement that reinforces the positive picture. Zefiro Methane has successfully plugged two more oil and gas wells in Cuyahoga Valley National Park near Cleveland, Ohio. This marks the company's second contract within the national park, following the National Park Service (NPS) highlighting Zefiro's first remediation project in a dedicated project profile. A new exploration contract from the Ohio Department of Natural Resources also expands the company's service offering to include well inspections and preparation ahead of permanent closure.
This contract demonstrates both Zefiro's technical capabilities and its growing acceptance among public-sector clients. Ohio plays a key role, ranking among the company's most dynamic markets. Cuyahoga Valley National Park attracts millions of visitors each year and is located in a densely populated region around Cleveland, Akron and Canton with around four million inhabitants. A total of 1,800 abandoned wells in federal national parks are far more than ecological relics; they can threaten public safety and surrounding communities. One case in which hikers discovered a leaking well because escaping methane was clearly audible shows how tangible the problem is. Such examples show that remediation does not depend solely on government programmes; it must also be addressed through local initiatives.
CEO Catherine Flax stated: "The exploration contract is a welcome addition in its own right. It brings Zefiro into an earlier stage of the remediation process, using the same teams that we deploy every day. And it gives us another way to support government agencies in addressing their inventories of orphaned wells."
On Track: From Record Revenue to an Operational Breakthrough
Zefiro significantly improved its operational performance in the 2025/26 financial year. Revenue climbed 31.1% to a record USD 42.5 million, while gross profit rose 66% to USD 12.4 million. At the same time, gross margin improved from 23.0% to 29.2%, and net loss fell from USD 10.8 million to 3.5 million. The jump in adjusted EBITDA is particularly telling: following a loss of USD 4.0 million in the previous year, the company has now achieved a positive figure of USD 3.8 million. Although integrating additional equipment and mobilising for major contracts may incur short-term costs, these measures are intended to create the conditions for further growth. The key will be to utilise the additional capacity efficiently and sustain the positive earnings trend.
By acquiring equipment from provider Viking Well Service for USD 4.3 million, Zefiro has expanded its fleet by five drilling rigs. According to the company, this unlocks around USD 10 million in additional annual revenue capacity. At the same time, the specialist is now active in 15 US states and can use its existing infrastructure for a range of services. Alongside well decommissioning, methane measurement and monitoring are gaining importance, as these services require comparatively little additional investment and, according to the company, can enable higher margins. The company also has the opportunity to unlock further revenue by generating carbon credits. Management is pursuing a growth strategy that combines organic expansion with targeted acquisitions and could generate annual revenue of around USD 100 million in the medium term.
Investment Highlights
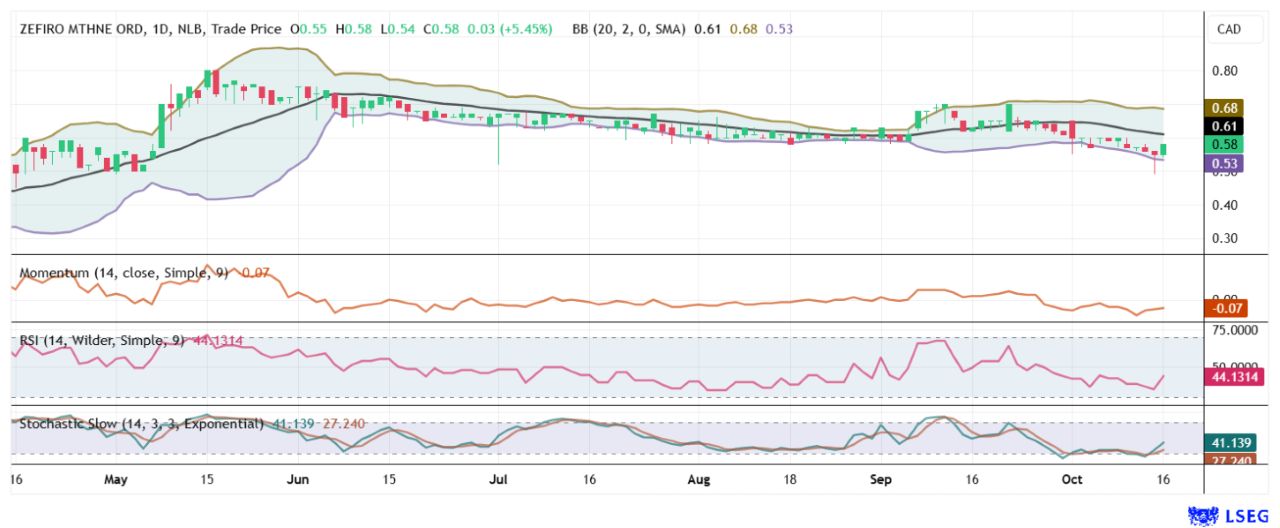
ZEFIRO METHANE (0.57 CAD | ZEFI | WKN: A3DVHU | ISIN: CA98926D1069)
Specialist in the decommissioning of orphaned oil and gas wells in the US – a market with an estimated value of USD 400 to 600 billion, currently operating in 15 US states
Integrated business model combines well remediation, methane measurement, environmental services and the generation of high-quality carbon credits
More than 2 million abandoned oil and gas wells in the US create a long-term structural growth market
Rising revenues and positive EBITDA show that the operating business can already be scaled profitably
Strategic acquisitions expand the fleet, workforce and regional presence and further increase the annual revenue base
In addition to government programmes, demand is increasingly coming from energy, natural gas and infrastructure customers
AI data centres and the multi-billion-dollar expansion of US energy infrastructure open up an additional growth segment
Methane measurement and certified emissions credits are developing into high-margin earnings pillars with significant scaling potential
Strategic partnership with the Well Done Foundation opens up access to projects in up to 18 US states and strengthens the market position for the long term
Viking acquisition expands the fleet by five rigs and creates around USD 10 million in additional annual revenue capacity
New USD 11.5 million contract running through 2029 increases revenue visibility
Still-low market valuation at the level of one year's revenue in 2026/27 gives a price-to-sales (P/S) ratio of 1
At the 20th International Investment Forum, CEO Catherine Flax answered analysts' questions and provided an outlook for 2027.
Conclusion: An Environmental Services Provider Benefiting from Tailwinds in the Oil and Gas Sector
The outstanding fundamentals warrant a closer look. GBC Research expects revenue of around USD 57.92 million and EBITDA of USD 10.02 million for the 2026/27 financial year. By 2028/29, revenue is expected to grow to USD 75.21 million and EBITDA to USD 15.04 million. Based on these forecasts, the P/S ratio is around 1.0 for 2026/27 and falls to approximately 0.7 for 2027/28. The research firm sees further share price potential and sets a price target of CAD 2.15; relative to the current share price used as the basis, this represents upside of just under 250%.
This valuation reflects a combination of government contracts offering multi-year predictability, growing private-sector business, and a business model that benefits from the remediation of neglected infrastructure. For investors, the main focus is on profitable contract execution, utilisation of the expanded fleet, and further margin expansion. With continued momentum, the company could therefore significantly expand its position in the American well remediation market. For analysts, it is clear: The newly published order backlog is likely to send a wake-up call through trading floors.
IIF moderator Lyndsay Malchuk in conversation with CEO Catherine Flax about the growing threat of methane emissions and further expansion plans.
This update follows the initial report dated 17.07.2026 and a further update dated 05.10.2026