America's Legacy Oil and Gas Wells Open Up a Billion-Dollar Market
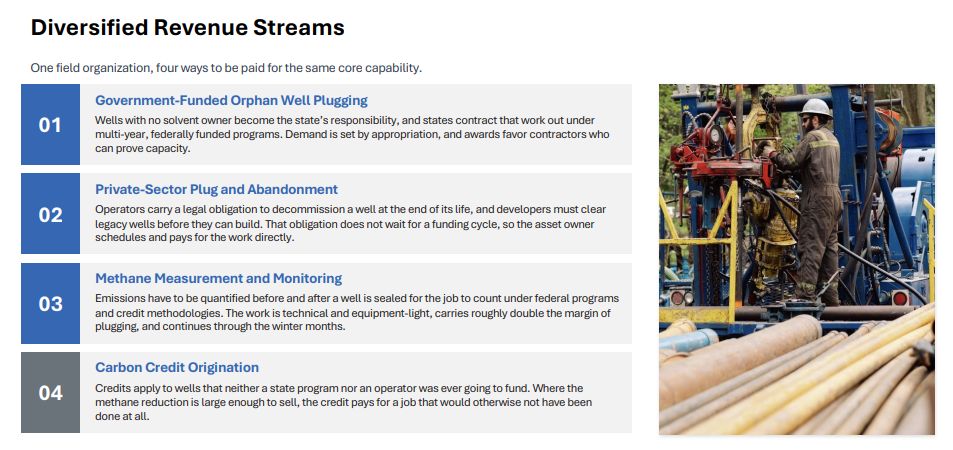
The problem is ubiquitous and easy to grasp. Millions of abandoned and orphaned oil and gas wells present the US with an enormous environmental and economic challenge. Many of these legacy wells release climate-damaging methane, while others block valuable land for new energy and infrastructure projects. This is precisely where Zefiro Methane comes in. The environmental services provider measures methane emissions, plugs old wells and reclaims the affected land. Through its subsidiary Plants & Goodwin, the company covers key stages of the entire remediation process – from measurement and monitoring to well plugging and land restoration. Government support is likely to continue for years to come. Of the USD 4.7 billion allocated by the US Congress to remediate orphaned wells, around USD 4 billion is not due to be distributed until 2031. Around USD 778 million in corresponding formula funding has been allocated in Zefiro's core regions to date. If everything goes to plan, Zefiro could secure around a quarter of the contracts funded by the infrastructure programme there. This gives the company a promising starting position in a market where environmental protection increasingly coincides with economic interests and the expansion of energy infrastructure.
An Order Backlog of USD 40 Million Provides Visibility Through 2029
The government order backlog of around USD 40 million reported on October 19 provides additional planning certainty. The projects extend through June 2029, with around USD 4.9 million in revenue expected to be generated from them in the current quarter ending in December alone. Measured against record revenue of USD 42.5 million in the 2025/26 financial year, this is a significant contribution, even though the total order volume will naturally not be recognised in the short term. The largest individual order is a three-year contract worth USD 19.6 million with Ohio's environmental and resources authority to plug around 200 wells. This is supplemented by a government-funded contract worth USD 11.5 million, with work due to begin in November. The reported order backlog comprises government projects only and excludes private customer orders. This is an important point: Zefiro thus has two sources of demand that can complement each other. The multi-year government project pipeline improves capacity planning, while private orders offer additional revenue opportunities and often involve shorter lead times.
Viking Acquisition Is Emerging as a Growth Driver
The October 27 announcement shows that the equipment acquired from Viking Well Service in May 2026 is already having an impact. Zefiro has now signed a total of seven new Master Service Agreements (MSAs) with corporate customers, including two listed natural resources companies. Five of these seven framework agreements have already generated revenue. The financial performance of the acquired capacity is particularly interesting: in August and September, Zefiro generated around USD 1.54 million in revenue from work attributable to the Viking acquisition. Annualised, this equates to more than USD 9 million, close to the additional annual capacity of around USD 10 million originally indicated by management. Zefiro also now has active framework agreements with almost all major gas producers in the northeastern US. Although such contracts do not guarantee specific call-off volumes, they facilitate access to recurring orders and strengthen its position as a preferred service provider. At the same time, demand is growing as a result of new energy infrastructure and data centres. When orphaned wells are located on planned construction sites, they must be properly secured first. In Pennsylvania, for example, Zefiro has plugged nine gas wells on the site of a former coal-fired power station earmarked for a natural gas-powered data centre site.
A New Perspective on the Carbon Credit Market
The carbon credit market could now provide further strategic momentum. In early November, Zefiro announced its support for the new Orphaned Well Plugging Protocol developed by the certification organisation Isometric. The draft was published on October 15, and the public consultation remains open through November 14, 2026. The framework is intended to enable the generation of carbon credits from the permanent plugging of orphaned wells – based on direct methane measurements before remediation and subsequent verification of the plugging. Zefiro has previously sold carbon credits from such projects to institutional buyers such as Mercuria Energy America and EDF Trading. If the new protocol is finalised and specific projects are approved, the company could use its existing crews, equipment and measurement capacity to generate additional revenue. Importantly: The credits are intended to be eligible only for wells that are not already being remediated through public programmes and would remain unplugged without additional funding. The carbon business would therefore complement the existing contract model rather than replace it.
CEO Catherine Flax stated: "Zefiro has shown that institutional buyers are willing to pay for methane reductions from orphaned wells. We are therefore pleased to support Isometric's work on a protocol based on direct field measurements. This is an additional opportunity for our shareholders. Carbon finance will enable us to plug abandoned wells that are not covered by public programmes while using the same crews and equipment that already serve our government and private customers."
Investment Highlights
ZEFIRO METHANE (0.66 CAD | ZEFI | WKN: A3DVHU | ISIN: CA98926D1069)
Specialist in plugging orphaned oil and gas wells in the US – a market with an estimated volume of USD 400 to 600 billion across 18 US states
Integrated business model combines well remediation, methane measurement, environmental services and the generation of high-quality carbon credits
More than 2 million abandoned oil and gas wells in the US create a long-term structural growth market
Dynamic revenue growth with revenue of USD 42.5 million in the 2025/26 financial year (up 31%)
Positive EBITDA performance shows that operations can already be scaled profitably
Strategic acquisitions expand the fleet, workforce and regional presence and further increase the annual revenue base
Alongside government programmes, demand is increasingly coming from energy, natural gas and high-tech infrastructure customers
Methane measurement and certified emissions credits are developing into high-margin earnings pillars with significant scaling potential
Strategic partnership with the Well Done Foundation provides access to projects in up to 18 US states and sustainably strengthens the market position
Viking equipment acquisition adds five rigs to the fleet and creates around USD 10 million in additional annual revenue capacity
New USD 11.5 million contract running through 2029 increases revenue visibility
Environmental remediation, energy infrastructure, methane abatement and emissions data in one integrated business model
Stock market valuation at micro-cap level, but with millions of dollars in revenue
At the 20th International Investment Forum (IIF), CEO Catherine Flax answered analysts’ questions and provided an outlook for 2027.
Analysts See Significant Potential – Financing Strengthens Financial Flexibility
The analysts at GBC Research believe Zefiro is capable of a strong growth spurt. For the 2026/27 financial year, they forecast revenue of around USD 57.9 million, EBITDA of approximately USD 10.0 million and net profit of USD 4.2 million. By 2028/29, EBITDA is expected to rise to around USD 15.0 million. The price target is CAD 2.15 (USD 1.50) and signals significant upside potential based on the share price of CAD 0.67 quoted in the original report. However, these expectations depend largely on Zefiro efficiently executing its order backlog, further utilising Viking's capacity and stabilising margins.
The company secured additional financial headroom on October 23 through a private placement raising gross proceeds of CAD 5 million. A total of 7,575,758 units were issued at CAD 0.66 each, each consisting of one share and half a warrant. The warrants entitle holders to subscribe for additional shares at CAD 0.80 within 30 months. Notably, the financing took place at just over 10% above the last traded market price. Investors clearly associate the attached warrant with good medium-term return prospects.
Conclusion – From Well Remediation Specialist to Diversified Environmental Services Provider
Zefiro Methane is developing its investment story on several levels. The government order backlog of around USD 40 million provides a baseline level of capacity utilisation for several years, while the Viking acquisition is already generating measurable revenue and new customer relationships. The potential resumption of methane credit generation also adds further revenue potential that could build on existing operational capabilities. Support for the Isometric protocol is an important step in this regard, although it has yet to materialise.
The latest capital raise improves financial flexibility and opens up options for further growth. If management succeeds in consistently utilising existing capacity and consolidating margins, Zefiro could enter a new corporate phase. For investors willing to take risks, the share therefore remains a highly attractive growth investment – one that, with increasing breadth and operational penetration, can turn into a medium-term value story.
IIF moderator Lyndsay Malchuk talks to CEO Catherine Flax about the growing threat from methane emissions and further expansion plans.
This update follows the initial report dated 17.07.2026 and a further update dated 20.10.2026