A billion-dollar problem becomes a growth driver
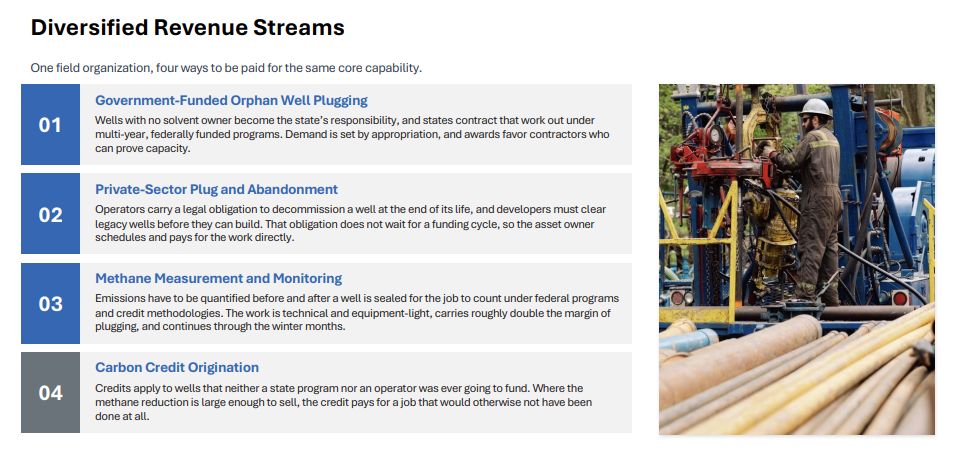
The problem is widespread and easy to grasp. Millions of orphaned oil and gas wells make the US a vast remediation market – and this could turn into an exceptionally lucrative business for Zefiro Methane. Many of these wells continue to release methane, a greenhouse gas whose climate impact over a period of 20 years is more than 80 times as strong as that of CO₂. The US Congress alone has allocated USD 4.7 billion for plugging orphaned wells; around USD 4 billion is set to flow into corresponding programmes by 2031. Around USD 778 million in funding has already been allocated in Zefiro's core regions – an enormous pool of public-sector demand from which the company can secure contracts. Through its subsidiary Plants & Goodwin, Zefiro has more than 50 years of operational experience and covers the entire remediation chain, from methane measurement and professional well plugging to land reclamation. The distinctive feature: Zefiro earns money not solely from climate protection, but from a tangible, publicly and privately funded service with a substantial backlog of work. Millions of leaking wells are turning into a long-term billion-dollar market – and Zefiro is positioning itself as a specialist beneficiary of this development.
More machinery, more markets, more revenue: Zefiro shifts up a gear
The current driver of operational growth is the integration of the equipment acquired from Viking Well Service. The five additional drilling rigs significantly expand capacity and, according to the company, open up annual revenue potential of up to USD 10 million. The initial figures show how quickly this investment can pay off: Viking rigs generated around USD 1.54 million in revenue in August and September 2026 alone. In the first quarter of the 2027 financial year, the new crews were also deployed in Indiana and Michigan for the first time – an important step beyond the existing core markets. Seven new Master Service Agreements with corporate customers, including two listed natural resources companies, further broaden access to the private market; five of these agreements have already generated initial revenue.
The quarterly figures show an operational improvement
In the first quarter of the 2027 financial year, Zefiro generated revenue of USD 12.1 million, up 30.7% on the previous quarter. Revenue remained almost stable compared with the prior-year quarter; however, adjusted for a sale of carbon credits at that time, this represents an increase of 2.8%. Gross profit reached USD 2.5 million, while the gross margin improved from 18.6 to 20.4% compared with the final quarter of the 2026 financial year. Particularly important is the return of adjusted EBITDA to positive territory. Following a loss of USD 0.6 million in the previous quarter, it now stood at USD 0.1 million. At the same time, the net loss narrowed from USD 2.8 million to USD 2.4 million, a sequential improvement we expect to see every quarter.
A look at costs shows why this development should not yet be interpreted as a completed turnaround. Operating expenses rose to USD 4.2 million in the quarter from USD 2.8 million in the prior-year period, with around USD 0.9 million attributable to non-cash items such as share-based compensation and depreciation. The expansion of field crews, higher fuel costs and the commissioning of additional rigs also initially weigh on the cost base. At the same time, cost efficiency improves when more drilling rigs and crews are continuously deployed and fixed costs are spread across a larger volume of orders. This is where the operating leverage for the coming quarters lies: if capacity utilisation improves and pricing discipline is maintained, gross profit could grow significantly faster than revenue.
Order backlog and financing create scope for planning
A key foundation for the current expansion is the government-funded order backlog of around USD 40 million, which extends through June 2029. This includes, among other things, a USD 19.6 million contract from Ohio's environmental ministry to remediate around 200 wells, as well as another government-funded project worth USD 11.5 million. For the second quarter of the 2027 financial year, the company initially expects around USD 4.9 million in work to be carried out from the government-funded order backlog, with the bulk of the remainder spread over subsequent years. Added to this are the new private-sector framework agreements, which open up additional business opportunities but do not represent guaranteed minimum revenues. To finance growth, Zefiro completed a private placement of CAD 5 million in October 2026 – an important liquidity buffer for personnel, operating resources and the execution of the extensive project pipeline. Potential subsequent option exercises at higher share prices will further increase this financing capacity.
A dual earnings opportunity: Well remediation meets the growing carbon market
Alongside the traditional remediation business, a second revenue model could gain importance in the future: generating methane credits. Zefiro has contributed to the development of the new Isometric protocol for plugging orphaned wells, which could enable the generation of credits to resume once the review process has been completed. Requirements include measuring methane emissions directly on site before remediation and subsequently having the permanent plugging independently verified. The model is intended in particular to cover wells whose remediation is not already planned under public programmes and would probably not take place without additional funding. This could allow Zefiro to use existing measurement technology, personnel and equipment as an additional revenue stream without having to build an entirely new operating business.
CEO Catherine Flax stated: "Zefiro has demonstrated that institutional buyers are willing to pay for methane reductions from plugging wells. We are therefore pleased to support Isometric's work on a protocol based on direct field measurements. This is an additional opportunity for our shareholders. Carbon finance will enable us to plug abandoned wells that are not covered by public programmes while using the same crews and equipment that already serve our government and private customers".
Investment Highlights
ZEFIRO METHANE (CAD 0.62 | ZEFI | WKN: A3DVHU | ISIN: CA98926D1069)
· Specialist in plugging orphaned oil and gas wells in the US – a market with an estimated value of USD 400 to 600 billion in 18 US states
· Integrated business model combines well remediation, methane measurement, environmental services and the generation of high-quality carbon credits
· More than 2 million abandoned oil and gas wells in the US create a long-term structural growth market
· Dynamic revenue growth with revenue of USD 12.1 million in the first quarter of the 2026/27 financial year (up 30.7%)
· Positive EBITDA performance shows that the operating business can already be scaled profitably
· Strategic acquisitions expand the fleet, workforce and regional presence and further increase the annual revenue base
· In addition to government programmes, demand is increasingly coming from energy, natural gas and high-tech infrastructure customers
· Methane measurement and certified emissions credits are developing into high-margin earnings pillars with significant scaling potential
· Strategic partnership with the Well Done Foundation provides access to projects in up to 18 US states and strengthens the market position over the long term
· Viking acquisition expands the fleet by five rigs and creates around USD 10 million in additional annual revenue capacity
· New USD 11.5 million contract running through 2029 increases revenue visibility
· Environmental remediation, energy infrastructure, methane abatement and emissions data in one integrated business model
· Micro-cap stock market valuation, but with millions of US dollars in revenue
An invitation to the Zefiro Investor Day
As part of the International Investment Forum, a "ZEFIRO INVESTOR DAY" will take place on Thursday, November 19. CEO Catherine Flax and Senior Vice President Luke Plants will answer analysts' questions and provide an outlook for 2027. The event starts at 17:00 CET.
CLICK HERE to register
Your questions for Zefiro
What would you like to ask Zefiro? Send your question/s by November 18, 2026, to Markus Nellessen, Head of Investor Relations at Apaton Finance: m.nellessen@apaton.com. We will collect all questions and have them answered during the Investor Day.
Analysts see significant potential
Analysts at GBC Research see significant growth potential for Zefiro and believe the company can achieve a substantial increase in earnings in the coming financial years. Their forecasts paint a picture of a service provider that could gradually reach a new level of earnings as fleet utilisation increases, project volumes rise, and the cost structure improves. For the 2026/27 financial year, GBC forecasts revenue of around USD 57.9 million, EBITDA of approximately USD 10.0 million and net profit of around USD 4.2 million. The analysts expect not only continued revenue growth, but above all a sharp improvement in operating profitability. The medium-term outlook is also ambitious: EBITDA is expected to grow to around USD 15.0 million by the 2028/29 financial year. GBC's price target of CAD 1.99 or USD 1.42 underlines this positive assessment. Based on the CAD 0.67 share price used in the original report, this implies considerable theoretical upside potential.
However, these estimates are subject to clear operational requirements: Zefiro must convert its large order backlog into revenue as planned, consistently utilise the additional Viking capacity and improve gross margins at the same time. The analysts are therefore counting not only on a growing market, but on the transition from a capacity-intensive expansion phase to an increasingly profitable business model. The forecasts should be understood as GBC Research's assessment, not as assured corporate targets or guaranteed results.
Conclusion: Zefiro on the verge of becoming a scalable environmental champion
Zefiro Methane is increasingly gaining strategic breadth and operational substance. The government contracts worth around USD 40 million provide a reliable revenue base through 2029 and facilitate long-term planning of staffing and machinery capacity. In parallel, Viking fleet integration is becoming a tangible growth driver. The additional drilling rigs are already generating revenue, providing access to new regions and opening further doors to private-sector industrial customers through seven framework agreements. The financial performance also deserves attention. With quarterly revenue of USD 12.1 million and adjusted EBITDA back in positive territory at USD 0.1 million, initial progress towards operating profitability is becoming evident. Furthermore, Zefiro could establish an additional revenue stream with its planned return to the methane credit market, without having to fundamentally expand its infrastructure. Participation in the Isometric protocol is an important prerequisite, but final adoption and the actual generation of credits are still pending.
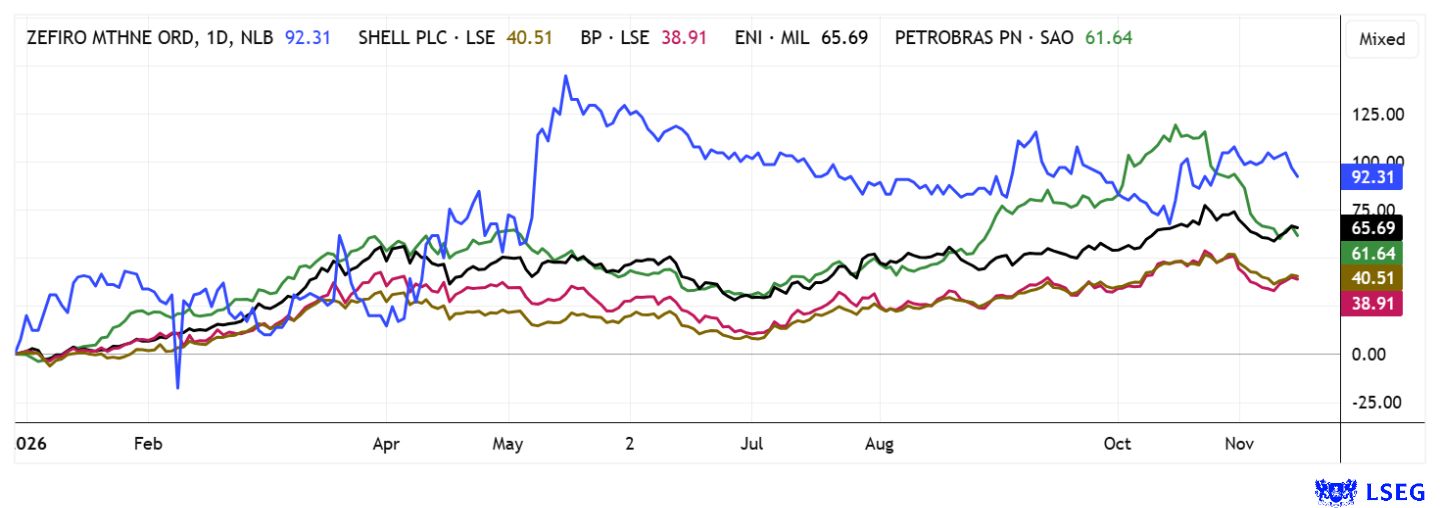
A comparison with major oil and gas companies illustrates that Zefiro operates in a high-margin environment. The crux: What others leave behind in the form of legacy liabilities and neglected well sites fills the remediation specialist's coffers. In the 2026 return comparison, the share is the sector champion, with a gain of over 92%. Returns range from 38% to 92%. Overall, the sector has performed exceptionally well compared with the major indices so far this year.
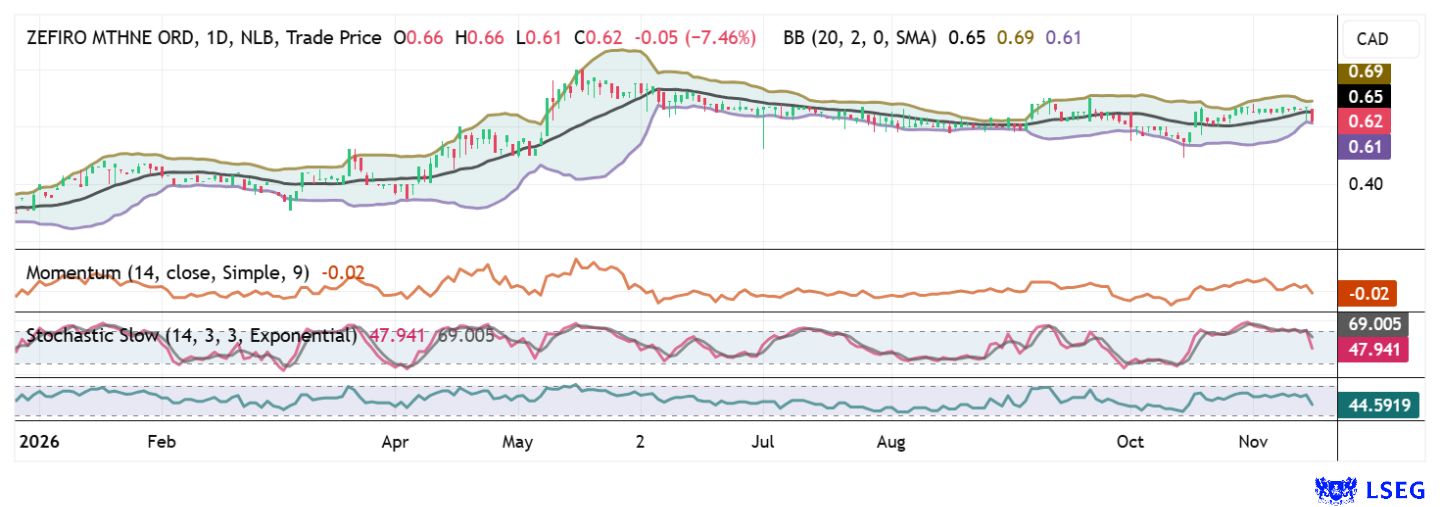
With rising quarterly revenue, adjusted EBITDA back in positive territory, additional capacity and a long-term order backlog, Zefiro has established important prerequisites for the next phase of growth. The sequential improvement shows that the company can keep its fleet fully utilised on a sustained basis. This improves the margin profile and turns the wealth of orders into sustainably positive cash flows. A swift continuation of the upward trend since autumn 2025 is likely, particularly when the “Tax Loss Season” ends in Canada at the end of November.
IIF moderator Lyndsay Malchuk speaks with CEO Catherine Flax about the growing threat posed by methane emissions and the company's further expansion plans.
This update follows the initial report dated 17.07.2026 and a further update dated 04.11.2026