Production Starts in Sangdong: The Decisive Step Has Been Taken
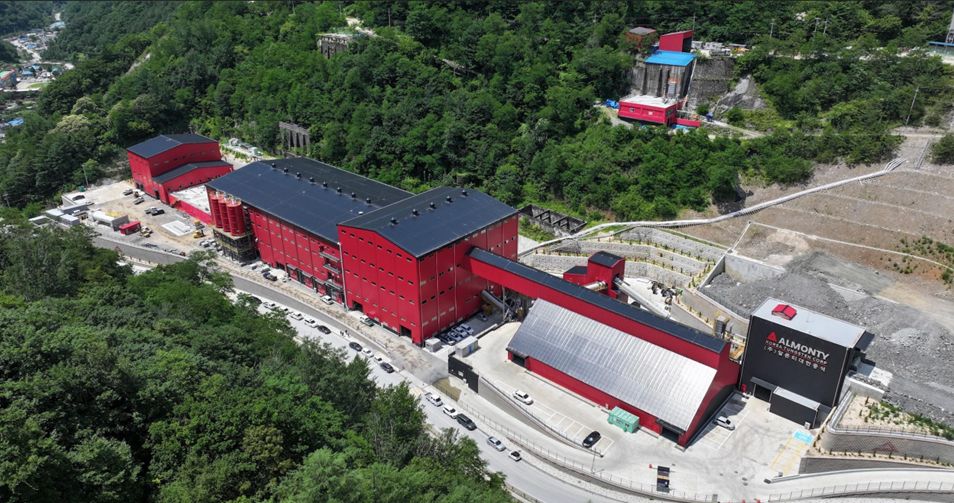
After more than three decades of inactivity, tungsten is once again being produced at the Sangdong mine in South Korea – for Almonty Industries, this is its most important operational milestone to date. With the operating permits for the processing plant and crusher granted on September 17, 2026, the final administrative hurdle has been cleared. The company can now commercially process the mined ore and sell tungsten concentrate. Sangdong is definitively moving from the construction and commissioning phase into commercial operation, with the gradual ramp-up of the plant now taking centre stage.
The long-term dimension is crucial: Once fully ramped up, Phase I is expected to achieve a throughput capacity of around 640,000 tonnes of ore per year. At the same time, the basis for a Phase II expansion already exists, which could eventually increase capacity to up to 1.2 million tonnes annually. Almonty has not just a production start, but a clearly defined growth path within the same world-class deposit. The capital market will likely need to increasingly recognise this shift. Whereas construction progress, permits and financing issues were previously the main topics of discussion, production volumes, margins and cash flows will determine the valuation in future.
A Structural Supply Deficit Works in Almonty’s Favour
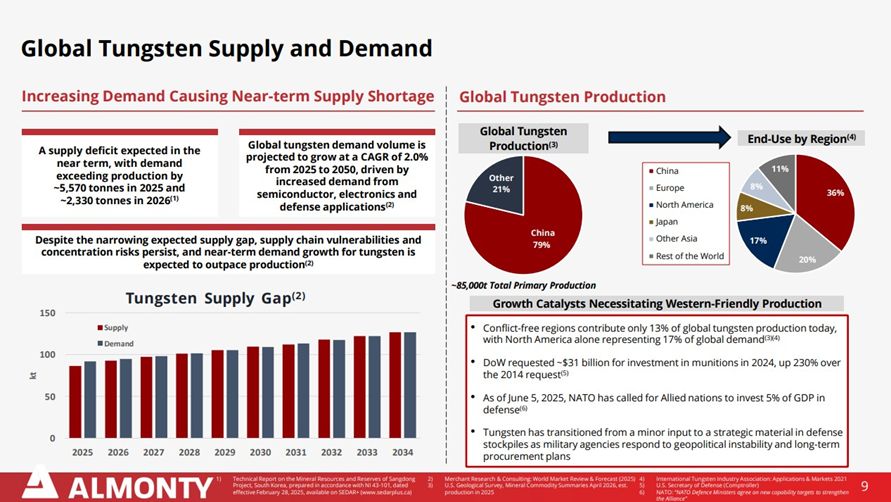
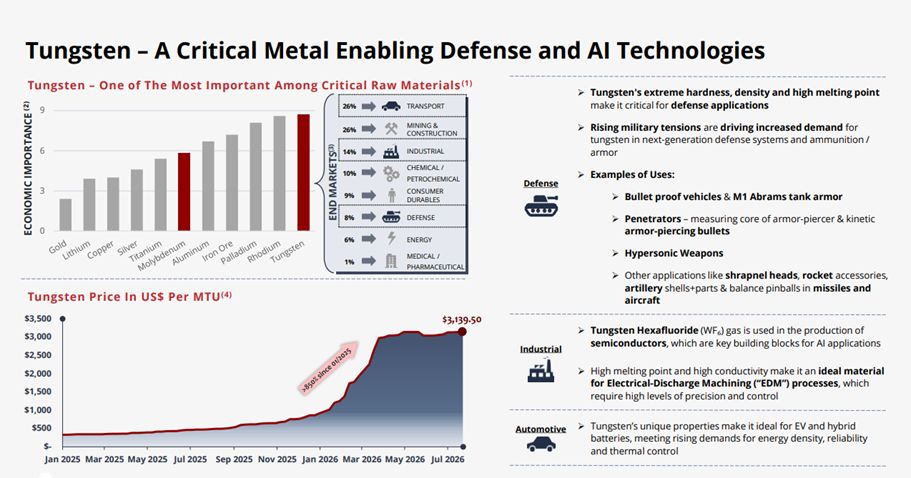
The situation on the global market is exceptional. According to the estimates cited by S&P Global, tungsten production outside China is expected to reach only around 22,000 tonnes of WO₃ in 2026, while the supply shortfall there is approximately 21,000 tonnes. At the same time, the APT price has already surged above USD 3,000 per MTU this year and is currently trading slightly below that at USD 2,700. Additional pressure comes from the US procurement restriction on tungsten from China, Russia, Iran and North Korea, which takes effect in January 2027, further enhancing the strategic value of Western and traceable supply sources. Heavy dependence on China affects not only mining but also downstream processing: the Middle Kingdom reportedly accounts for around 79% of global mining capacity and approximately 85% of APT refining capacity. New mines cannot eliminate this dependence in the short term, as permits, investment and the technical production ramp-up take years – a window of time in which established Western suppliers such as Almonty could be particularly sought after.
Montana’s Historic Tungsten District Will Complete the Picture in the Long Term
Alongside South Korea, the American project pipeline is developing into an increasingly interesting second strategic focus. The Gentung project in Montana is located in a region with historic tungsten production and therefore has particular geological and geopolitical significance. The entire district is attracting additional attention through exploration work at Red Mountain Mining's neighbouring Pioneer Tungsten Project. Initial sampling there reported tungsten grades of up to 0.32% WO₃. These grades are of a similar order of magnitude to those at Almonty's immediately adjacent Gentung deposit, for which a mineral resource of 6.83 million tonnes at 0.315% WO₃ was reported. The current systematic sampling programme is now intended to better define the extent, geometry and continuity of the near-surface mineralisation. If the results are positive, drilling could follow. For Almonty, this development is strategically relevant because it concerns not only its own project, but could also underline the significance of an entire tungsten belt in Montana.
CME Group Makes Tungsten Tradable Through Futures for the First Time
Another significant development comes from CME Group. The world's leading futures exchange operator plans to introduce tungsten futures as early as the first quarter of 2027, subject to regulatory approvals. The cash-settled contract is to be based on the Fastmarkets price for ammonium paratungstate (APT) and offer industrial companies a standardised means of price hedging and budget planning for the first time. With annual global production of approximately 85,000 to 95,000 tonnes and a market value of more than USD 20 billion, this is an important step towards professionalisation that is likely to increase the visibility and tradability of the strategic metal. Until now, market participants have largely had to manage price risks through individual agreements and the physical spot market, making long-term calculations more difficult. A standardised futures product could integrate tungsten more closely into the institutional commodities infrastructure – a signal that the metal is increasingly being perceived as a strategic market in its own right.
Long-Term Offtake Agreements Provide a Solid Sales Base
It is particularly valuable for Almonty that around 90% of planned Phase I production from Sangdong is already secured by the offtake agreement with Global Tungsten & Powders, which has recently been extended to 21 years. The total contract volume amounts to 4.41 million MTU, with minimum annual offtake volumes of 210,000 MTU following the ramp-up. This agreement significantly reduces sales risk, while the key operational task now is to ramp up production steadily and deliver the agreed volumes reliably. The contractual partner belongs to Austria's Plansee Group and is embedded in a major industrial tungsten processing network. This long-term offtake commitment is a significant advantage for financing and planning mining operations, as Almonty does not have to sell a large proportion of its future production on the open market.
Investment Summary: An Overview of the Medium-Term Catalysts
· Phase 1: Commissioning and ramp-up at the Sangdong mine in South Korea are progressing on schedule
· Phase 2: Increasing mill capacity or building a new mill to reach a target of 1.2 million MTU per year
· Tungsten: 21-year offtake agreement concluded with GTP (USA)
· Increasing output at the Panasqueira mine in Portugal to up to 300,000 MTU over time
· Drilling programme for molybdenum launched
· Further processing of tungsten concentrate into tungsten oxide, which is used for semiconductors and batteries
· LOI for downstream project financing of USD 50 million with KfW
· Low production costs estimated at USD 126.80 per MTU (APT) - current market price approximately USD 2,700
· Production in the USA: Reactivation of the historic Gentung mine in Montana
· Inclusion of molybdenum as an additional source of cash flow in South Korea
Analysts Remain Optimistic – The Share Price Correction Makes Strategic New Investments More Affordable
The latest analyst estimates present a predominantly positive picture despite the sharp share price correction. According to LSEG Refinitiv, the average twelve-month price target from 12 analysts is around USD 22.94, with a range of approximately USD 12.98 to USD 32.84. B. Riley lowered its price target from USD 25 to USD 20 at the end of October; Stifel cut its target to USD 21, and Oppenheimer to USD 19. Goldman Sachs initiated coverage with a Neutral rating and a USD 13 price target. It should be noted that the initial price targets were based on a highly euphoric assessment of the overall situation in mid-2026 and are now being adjusted to the current price scenario.
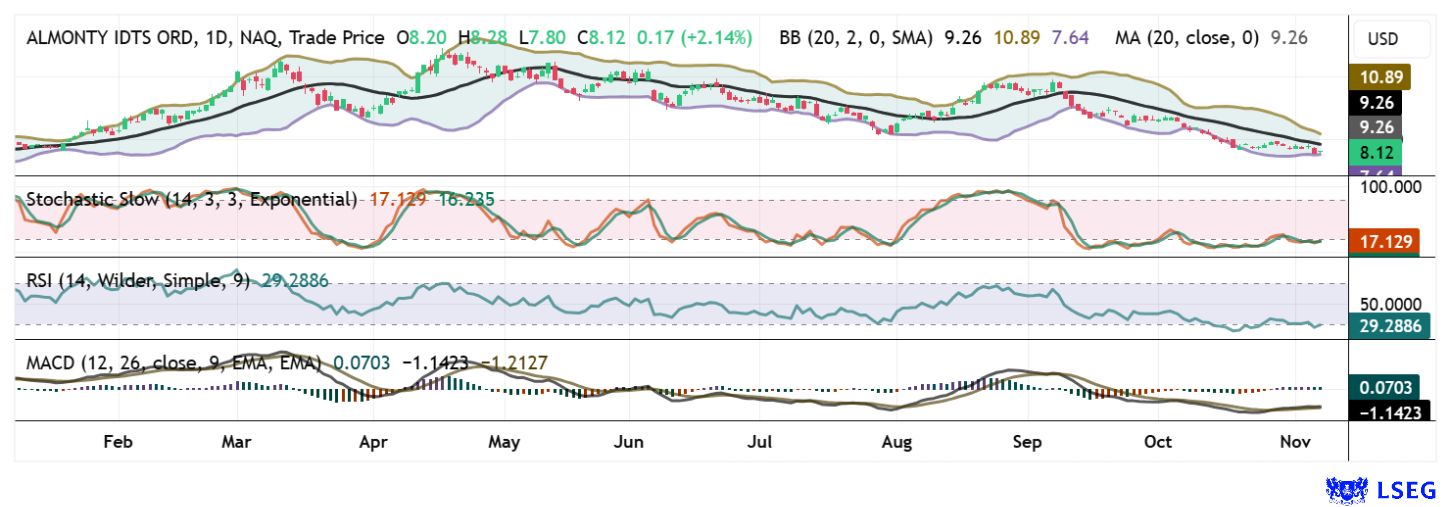
The current technical assessment identifies important support around USD 8 and outlines a possible recovery scenario above USD 12.90 into the USD 15 to USD 16 range; however, these chart levels remain scenarios and are not reliable price forecasts. The decline from an interim high of over USD 20 to around USD 8.70 recently illustrates how sharply the share price has repriced earlier expectations. A sustained revaluation is therefore likely to depend less on a short-term technical rebound than on proof that Sangdong actually achieves the planned volumes and financial metrics.
Conclusion: From Strategic Promise to Operational Supplier
With Sangdong, Almonty has delivered crucial proof: the company now has a production facility licensed for commercial operation in a geopolitically important market outside China, along with long-term secured customers. The structural supply deficit, the new US procurement rules and the planned CME futures exchange further strengthen the environment, without necessarily leading automatically to persistently high tungsten prices. The fundamental investment story has become significantly more robust with the start of production, and further share price performance now depends above all on a successful ramp-up, actual delivery volumes and the achievement of financial targets.
For risk-aware investors with a longer investment horizon, Almonty remains a very promising strategic commodity play. The combination of its own production, long-term offtake agreements and a commodity positioning increasingly in demand for geopolitical reasons gives the company a highly attractive starting point for the coming years.
Watch the latest video featuring CEO Lewis Black and IIF host Lyndsay Malchuk, discussing the challenges of building a Western defence supply chain.
This update follows our initial Report 12/2021.