Where Others See Contaminated Sites, Zefiro Sees Growth
For Zefiro Methane, America's contaminated sites, the legacy of more than a century of oil and gas production, are increasingly shifting from an environmental problem to a lucrative infrastructure market. Millions of abandoned and orphaned wells must be permanently plugged because methane continues to leak, posing climate, environmental, safety, and land-use risks. Through its subsidiary Plants & Goodwin, Zefiro has specialized in precisely this task and now covers nearly the entire value chain—from methane measurement and monitoring to plugging and decommissioning, land reclamation, and, in the future, the generation of carbon credits.
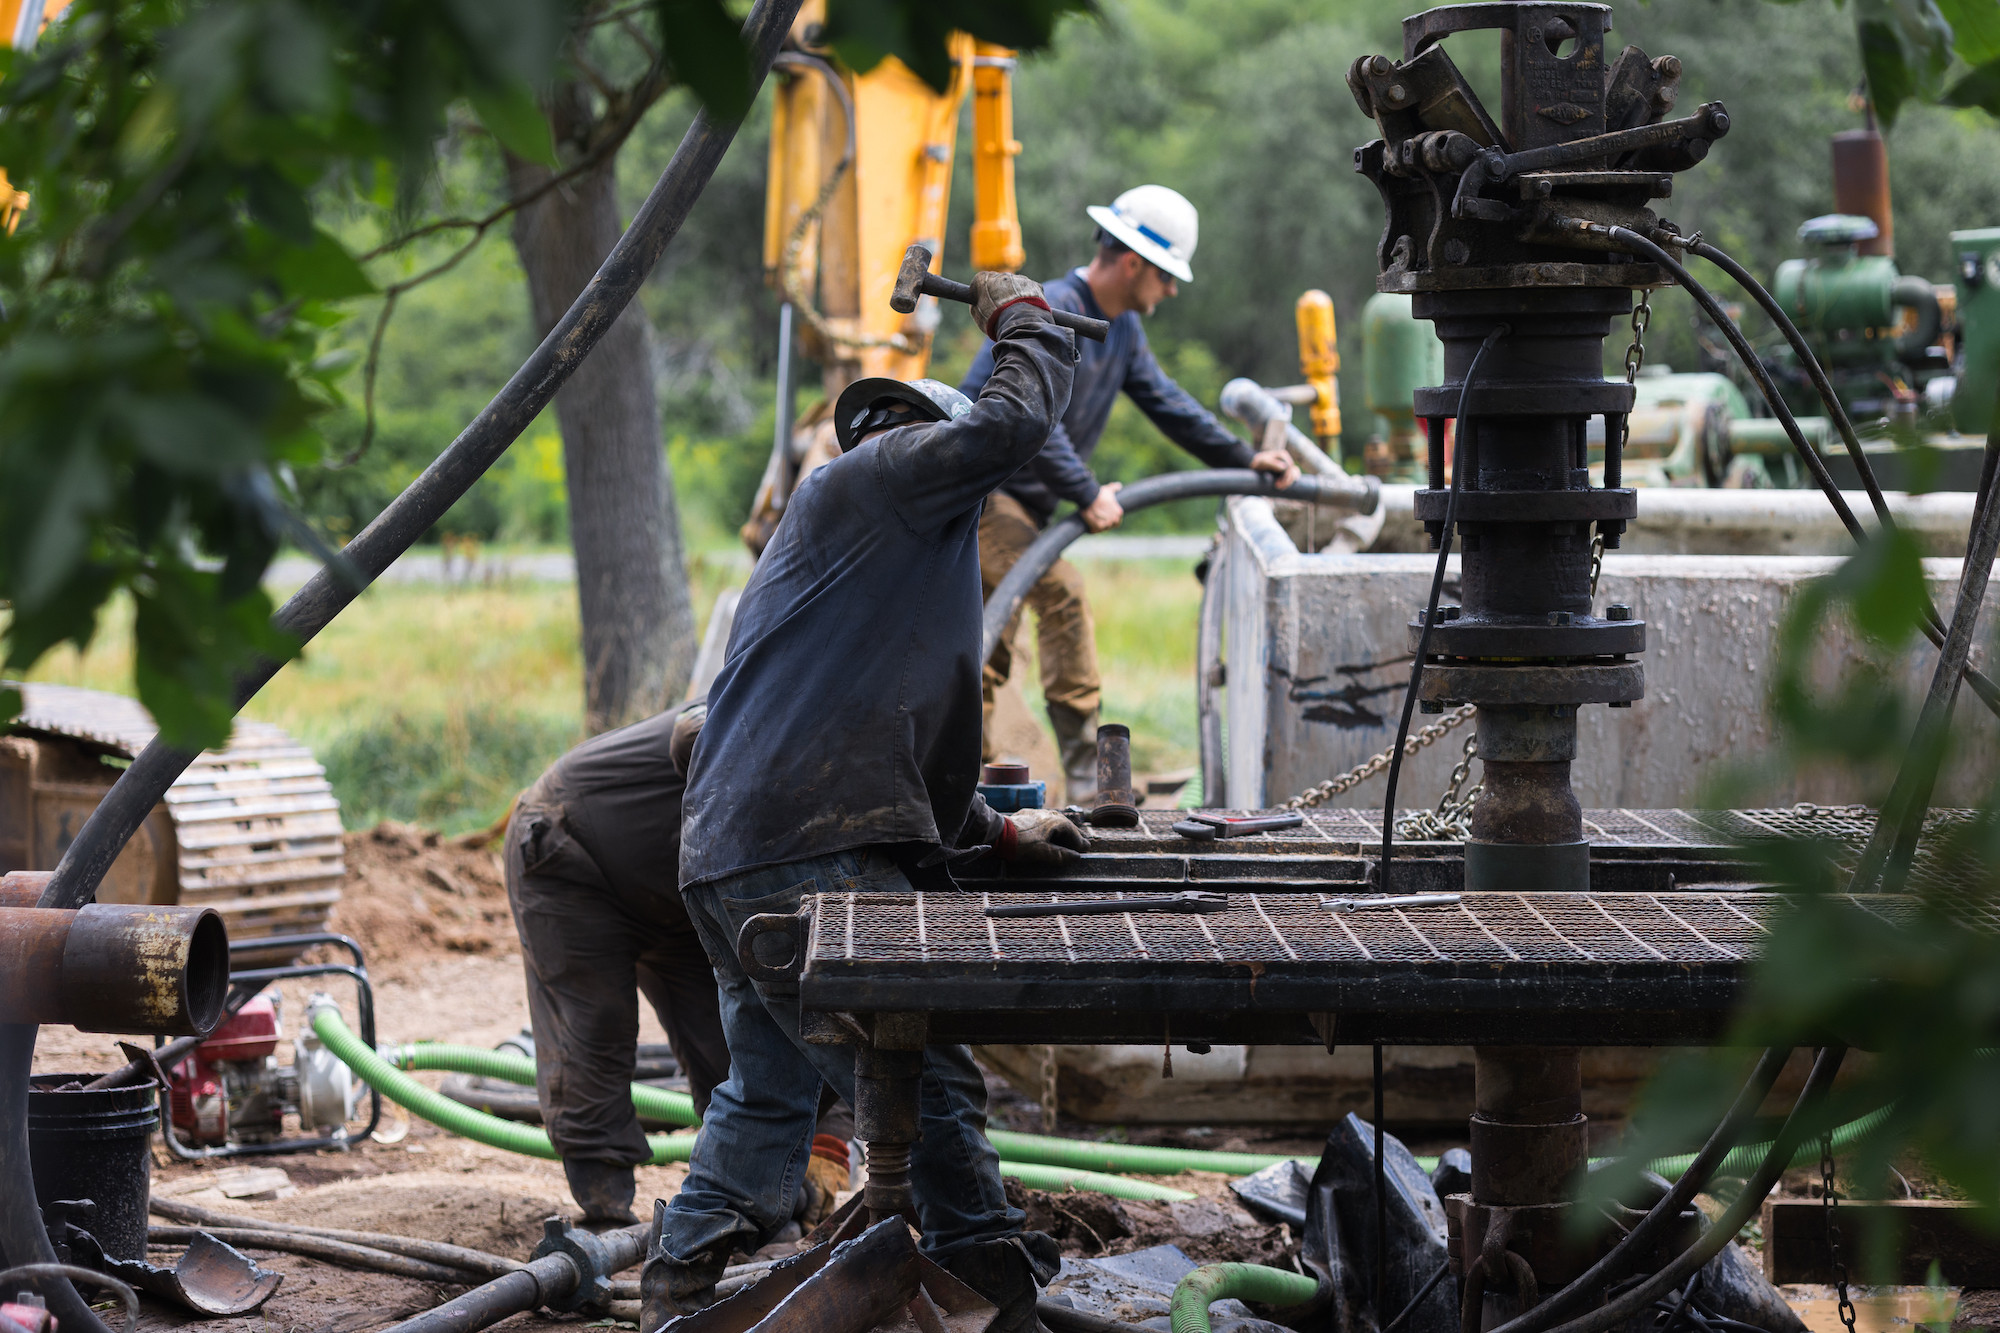
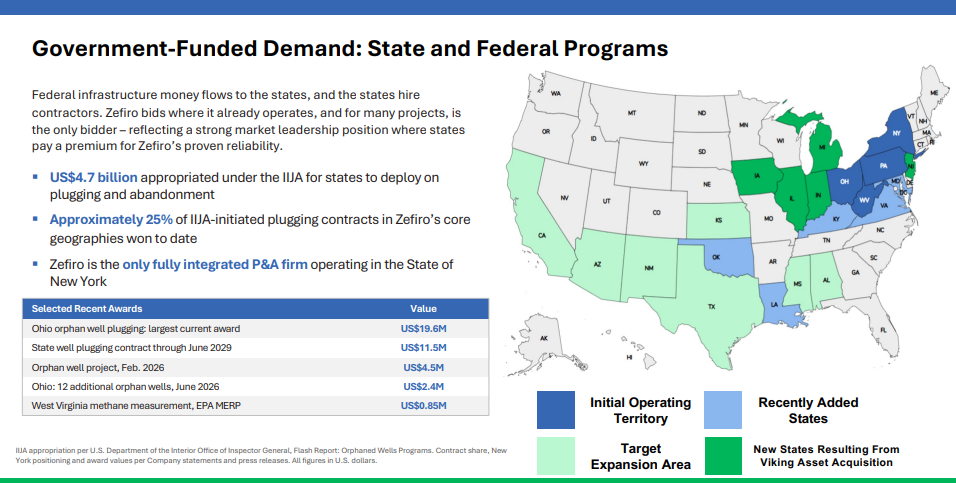
Strong momentum in this area is not coming solely from government remediation programs: Energy utilities, natural gas producers, and developers of power and data centre infrastructure increasingly need safe sites where orphaned wells do not hinder further use. With the acquisition of Viking Well Service's equipment fleet for USD 4.3 million, Zefiro has significantly increased its operational capacity, added five additional rigs, and, according to the company, expanded its annual revenue by approximately USD 10 million. At the same time, its geographic reach has now grown to 15 US states, while the partnership with the Well Done Foundation is opening up additional project opportunities.
The combination of operational remediation and data-driven methane management remains particularly attractive. A successfully plugged well not only eliminates a source of emissions but, following appropriate verification, can also provide the basis for tradable emission credits. This creates a long-term business model in which Zefiro can benefit from both the physical elimination of the problem and the documentation and monetization of avoided emissions.
Recent contracts demonstrate that this strategy is increasingly translating into predictable revenue. The USD 19.6 million contract from the Ohio Department of Natural Resources for approximately 200 prioritized drilling projects is already underway and is the largest government contract in the company's history to date. In addition, another state-funded contract worth USD 11.5 million was awarded in September, with work scheduled to take place from November 2026 through June 2029. Of this amount, approximately USD 3 million is expected to be recognized by the end of June 2027, while an additional USD 8.5 million is scheduled for recognition by June 2029. In addition, there are three other government-funded projects in Ohio and Pennsylvania worth approximately USD 1.9 million, as well as private clients in the natural gas, energy, and infrastructure sectors.
Record Figures Mark an Operational Turning Point
The latest figures were released yesterday! The 2025/26 fiscal year generated revenue of USD 42.5 million, a 31.1% increase compared to the previous year—a new record. Gross profit grew even faster, rising 66.0% to USD 12.4 million. The gross margin also improved from 23.0% to 29.2%. Despite strong business expansion, operating costs fell 10.2% to USD 14.4 million; as a result, the net loss fell from USD 10.8 million to USD 3.5 million. However, adjusted EBITDA appears to be particularly relevant for the operational assessment: After a loss of USD 4.0 million in fiscal year 2025, Zefiro achieved positive adjusted EBITDA of USD 3.8 million in 2026, an improvement of USD 7.8 million.
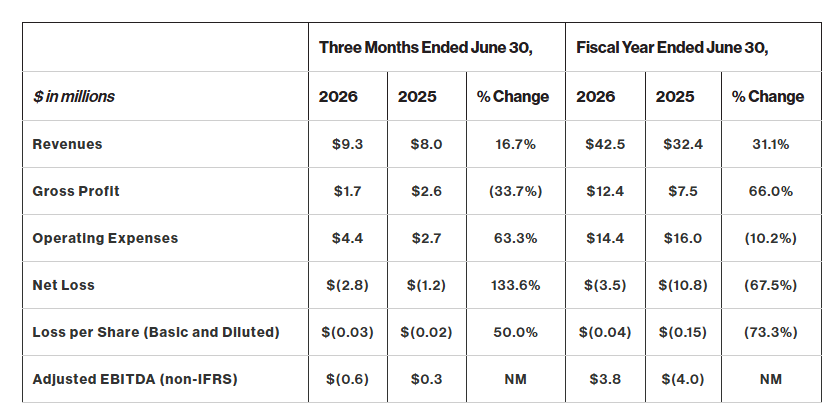
In the fourth quarter alone, revenue rose 16.7% to USD 9.3 million, although profitability was temporarily impacted by the integration of the Viking fleet, mobilization costs for the Ohio contract, additional hires, and a less favorable revenue mix. The resulting gross profit was USD 1.7 million, representing a margin of 18.6%, down from 32.8% in the same quarter of the prior year. Adjusted EBITDA for the fourth quarter was also negative at USD -0.6 million; however, management attributes these pressures to the expansion of new capacity required to fulfill the large order backlog in the future. In addition, the quarter included a one-time non-cash impairment charge of USD 0.5 million on Viking assets, as well as USD 0.7 million in stock-based compensation. For the full year, therefore, it is not so much the weaker mix in the final quarter as the significant jump in revenue, gross profit, and EBITDA that is significant.
Investment Highlights
ZEFIRO METHANE (CAD 0.64 | ZEFI | WKN: A3DVHU | ISIN: CA98926D1069)
- Specialist in the decommissioning of abandoned oil and gas wells in the US—a market with an estimated volume of USD 400 to 600 billion currently spanning 15 US states
- Integrated business model combines well remediation, methane measurement, environmental services, and the generation of high-value carbon credits
- More than 2 million abandoned oil and gas wells in the US create a long-term, structural growth market
- Dynamic revenue growth with expected revenue of USD 42.5 million in fiscal year 2025/26
- Positive EBITDA trend demonstrates that the operating business can already be scaled profitably
- Strategic acquisitions expand the fleet, workforce, and regional presence, further increasing the annual revenue base
- Demand is increasingly coming from energy, natural gas, and infrastructure customers, in addition to government programs
- AI data centres and the multi-billion-dollar expansion of US energy infrastructure are opening up an additional growth segment
- Methane measurement and certified emissions credits are emerging as high-margin revenue pillars with significant scaling potential
- Strategic partnership with the Well Done Foundation opens access to projects in up to 18 US states and sustainably strengthens the market position
- Viking acquisition expands the fleet by five rigs and creates approximately USD 10 million in additional annual revenue capacity
- New USD 11.5 million contract running through 2029 increases revenue visibility
- Environmental remediation, energy infrastructure, methane mitigation, and emissions data in an integrated business model
- Market capitalization at the micro-cap level, but with millions of US Dollars in revenue
Outlook: Strong Financial Results Followed by Meticulous Growth to Scale
The financial results now paint a significantly different picture than they did two years ago: USD 42.5 million in revenue, USD 12.4 million in gross profit, and USD 3.8 million in adjusted EBITDA mark clear operational progress. The improvement in profitability is particularly important, as Zefiro is no longer growing solely through additional projects but has also significantly expanded its gross margin and reduced operating costs. CEO Catherine Flax has the transition to profitability on her agenda; until then, the company will continue to scale up and integrate new teams into the business model. For 2026/27, the focus is on utilizing the five additional Viking rigs, executing the major Ohio contract, and monetizing the growing order backlog.
GBC and Cormark Forecast Further Growth
Although the latest figures have not yet been factored in, GBC Research continues to expect dynamic growth for Zefiro and most recently projected revenue of approximately USD 57.9 million and EBITDA of USD 10.02 million for 2026/27, followed by revenue of approximately USD 66.85 million and EBITDA of USD 12.22 million for 2027/28. Analysts view the combination of multi-year government contracts, additional Viking capacity, and a potential revival of the carbon credit business as key growth drivers and have set a price target of CAD 2.12 CAD or USD 1.50. ATB Cormark takes a more cautious approach, projecting a price target of CAD 1.00 and assigning Zefiro an "Outperform" rating. Notably: The latest figures still need to be processed by the research firms; Zefiro has already exceeded ATB Cormark's revenue estimate with USD 42.5 million. It will therefore be interesting to see what the final new price target turns out to be.
As part of the 20th International Investment Forum, CEO Catherine Flax will take questions from analysts and provide an outlook for 2027. Click here to register.
Conclusion: The Large Order Backlog As a Key Driver
Zefiro is entering the 2026/27 fiscal year with a significantly larger operational platform than it had 12 months ago. The combination of record revenue of USD 42.5 million, positive EBITDA, five additional rigs, operations in 15 US states, and long-term government contracts is noticeably changing the company's starting position. The key question now is whether Zefiro can operate its newly created capacity at a sufficiently high utilization rate while further expanding the margin improvement achieved in fiscal year 2026. If successful, methane monitoring, carbon credits, and private infrastructure clients could become additional revenue streams alongside traditional well plugging. This would imply significantly higher revenue than market participants currently estimate.
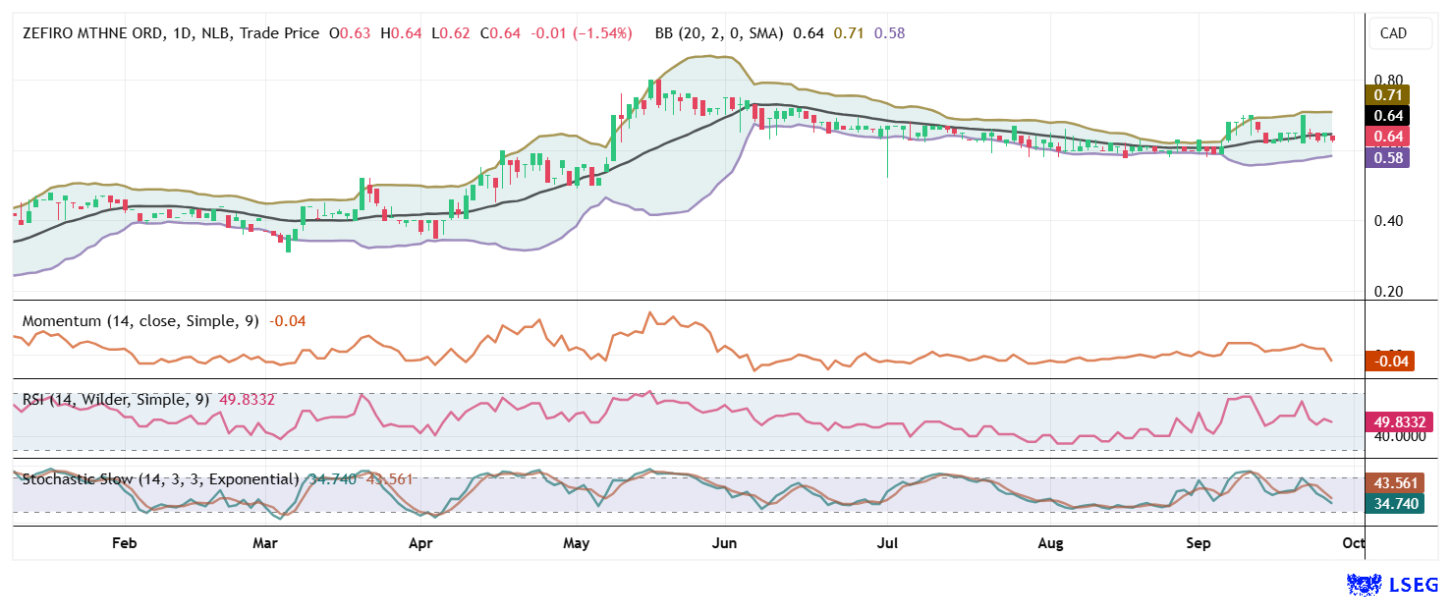
The real investment potential therefore lies less in a single major announcement than in the company's ability to translate the platform it has built over several years into rising revenue and sustainable cash flows. With a price-to-sales (P/S) ratio of 1.0 in 2026 and just 0.7 based on 2027 estimates, the stock is very attractively valued compared to its sector peers. Investors should brace themselves for strong quarters ahead, as Zefiro is working meticulously and with great motivation toward higher goals.
IIF host Lyndsay Malchuk speaks with CEO Catherine Flax about the growing threat of methane emissions and the company's further expansion plans.
This update follows the Initial Report dated July 17, 2026, and a further update dated September 14, 2026.